Categories
Arizona Living, Home Buying Advice, Seller ResourcesPublished August 18, 2026
What Should You Do With Your Home Equity? 6 Options to Consider
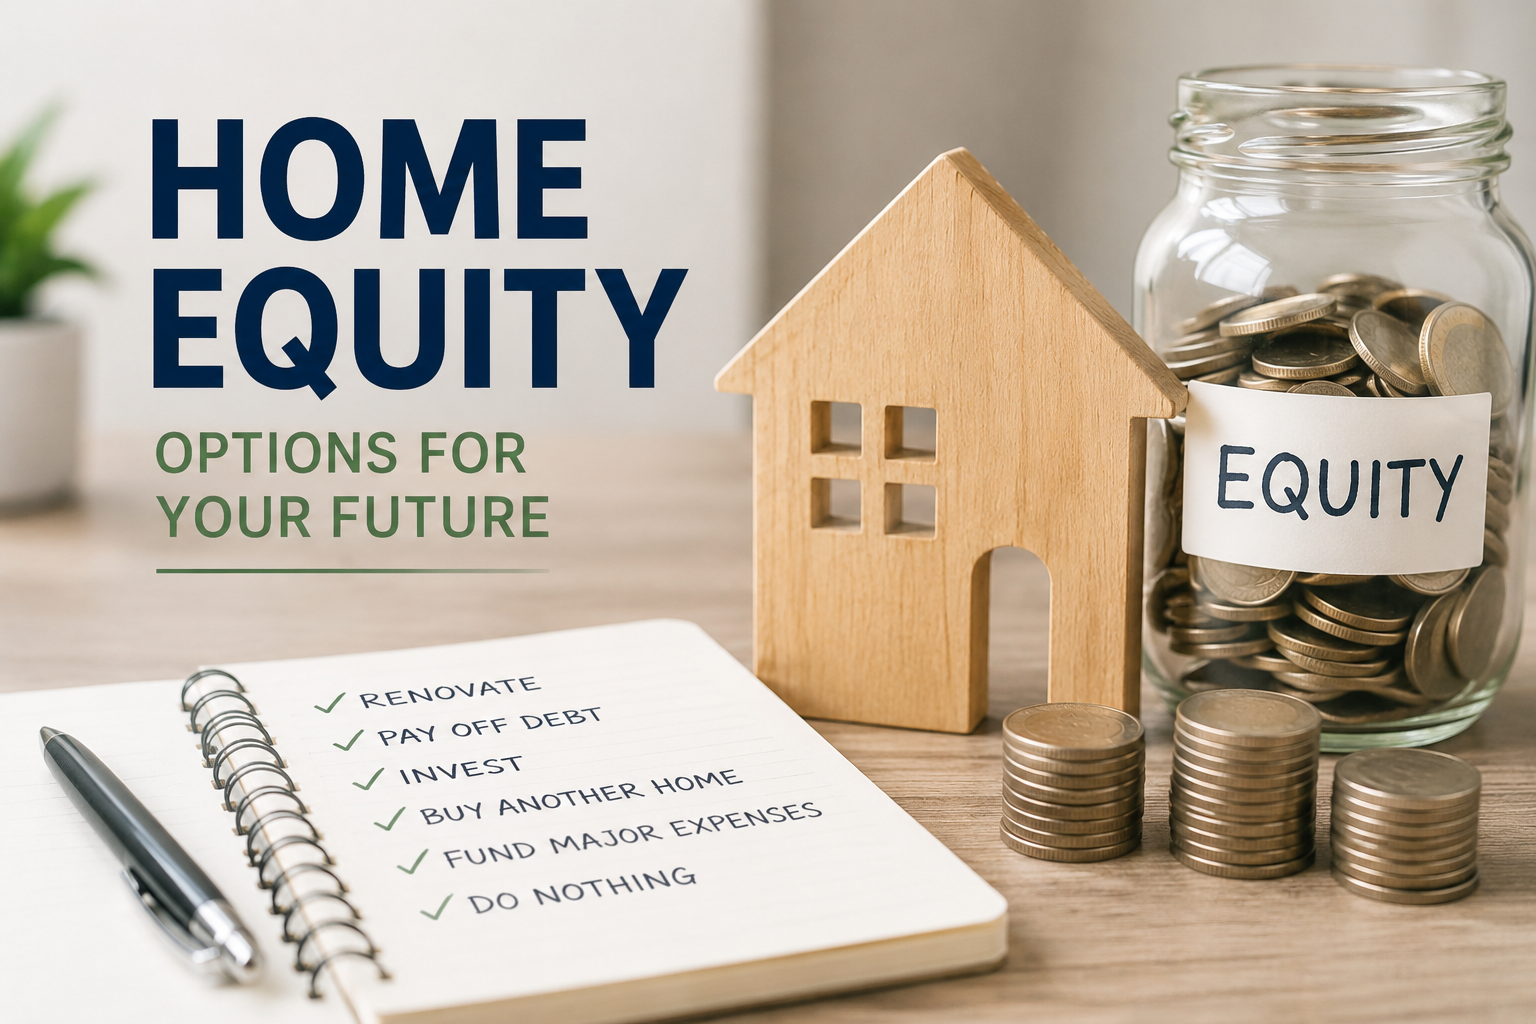
If you’ve owned your home for a few years—or even longer—there’s a good chance you’ve built up more equity than you realize.
Home equity can be one of your biggest financial assets, but unlike money sitting in a savings account, it isn’t always obvious what you should actually do with it. Should you use it to renovate? Pay off debt? Buy another property? Or is the smartest move simply leaving it alone?
The answer depends on your financial situation and your goals. Before making any decisions, it helps to understand what your equity represents and some of the options available to you.
First, What Is Home Equity?
Home equity is essentially the portion of your home that you own.
A simple way to estimate it is:
Current Home Value – Remaining Mortgage Balance = Estimated Home Equity
For example, if your home is worth approximately $550,000 and you owe $300,000 on your mortgage, you have roughly $250,000 in equity.
That doesn’t mean you have $250,000 available to withdraw tomorrow. Selling expenses, lending requirements, market conditions, and other factors all affect how much equity you could actually access.
Still, knowing approximately how much equity you have can be helpful when making bigger financial decisions.
So, what can you do with it?
1. Use Your Equity for Home Improvements
One of the most common reasons homeowners access their equity is to make improvements to the home they already own.
Depending on the project, renovations can make your home more enjoyable now while potentially improving its resale appeal later.
You might consider using equity for projects such as:
- Updating an outdated kitchen or bathroom
- Replacing flooring, windows, or roofing
- Adding usable living space
- Improving energy efficiency
- Updating an older HVAC system
- Creating a more functional backyard or outdoor living area
Here in Arizona, certain improvements can be especially valuable to homeowners. Updated air conditioning, energy-efficient windows, shade features, pools and functional outdoor spaces can all affect how buyers perceive a property.
Just remember: not every renovation gives you dollar-for-dollar value when you sell.
Before spending a significant amount on improvements, it can be helpful to understand which updates buyers in your particular neighborhood actually value.
2. Pay Off Higher-Interest Debt
Another option is using some of your home equity to consolidate higher-interest debt.
Credit cards and certain personal loans can carry significantly higher interest rates than some home-equity borrowing options. Consolidating that debt could potentially reduce the amount of interest you're paying.
But there is an important distinction to understand.
Credit card debt is unsecured. Borrowing against your home is secured by your property.
In other words, you're potentially turning debt that wasn't attached to your house into debt that is.
That doesn't automatically make it a bad idea, but it does mean this decision deserves careful consideration. Talking with a qualified lender or financial professional can help you compare the actual costs and risks before moving forward.
3. Use It Toward Another Property
For some homeowners, equity in their current home can help make purchasing another property possible.
That could mean buying:
- An investment property
- A vacation home
- A property for a family member
- A future retirement home
- Another primary residence before selling the current one
There are several ways this can potentially be structured, and the right option depends heavily on your finances, existing mortgage, interest rates and long-term plans.
This is also where understanding your actual market value becomes important.
Online estimates can give you a starting point, but if you're considering using your equity for another purchase, you'll want a more realistic idea of what your home could sell for in today's market.
4. Use It for a Major Expense
Homeowners sometimes consider accessing equity for significant expenses that would otherwise require a large amount of cash.
That might include college tuition, starting or expanding a business, major medical expenses, or another substantial financial need.
Because your home is likely one of your largest assets, having equity can give you options that someone without significant home equity may not have.
But having access to that money doesn't necessarily mean you should use it.
Before borrowing against your home for a major expense, look closely at the total cost of borrowing, repayment terms and how the additional monthly payment fits into your long-term budget.
5. Use Your Equity to Make Your Next Move
Sometimes equity isn't something you need to borrow against at all.
Instead, it becomes the money that helps you move from your current home into the next stage of life.
Maybe you've been thinking about:
- Moving into a larger home
- Downsizing
- Relocating
- Buying a home with a different layout
- Moving closer to family
- Purchasing a home better suited to your current lifestyle
In that situation, the equity from the sale of your current home may become a substantial down payment—or even allow you to purchase your next property with a much smaller mortgage.
This is one reason we encourage homeowners to know approximately where they stand even if they aren't planning to move immediately.
You don't have to be ready to sell to benefit from knowing what your home is worth.
6. Do Absolutely Nothing
Yes, this is an option—and sometimes it's the best one.
You don't have to "put your equity to work."
Every mortgage payment you make generally increases your ownership stake in the property, while changes in your home's value can increase or decrease your equity over time.
Leaving your equity untouched means you aren't taking on additional debt simply because it's available.
For homeowners with a low mortgage rate, manageable payment and no immediate need for the money, maintaining the status quo may make perfect sense.
Equity can simply remain part of your long-term financial picture until there's a compelling reason to use it.
How Much Equity Do You Actually Have?
This is where things get interesting.
Many homeowners have a general idea of what they paid for their home and what they still owe—but aren't sure what the property would actually sell for today.
And your purchase price from five, ten or fifteen years ago doesn't tell you much about your current equity.
Neither does your neighbor's sale or an automated online estimate.
Your home's value can be affected by its condition, upgrades, lot, location within the neighborhood, floor plan, current competition and recent comparable sales.
If you're considering making a financial decision based on your home equity, getting a realistic estimate of your home's current market value is a good place to start.
Your Home Is More Than Just a Place to Live
For many Arizona homeowners, their home represents one of the largest pieces of their overall net worth.
That doesn't mean you need to sell it, refinance it or borrow against it. But understanding the equity you've built gives you more information when you're making decisions about your finances and your future.
And sometimes, knowing your options is valuable even when you decide not to do anything at all.
Curious how much equity you may have in your home? We can help you get a realistic idea of what your property could be worth in today's market—without any pressure or obligation to sell.
Call or text us at (480) 382-8093, email us at admin@thegoodmantaylorteam.com, or visit thegoodmantaylorteam.com.
The Goodman Taylor Team
Expansion Partner | The Goodman Taylor Team | eXp Realty
or another way